Oil Prices Surge, UK Budget Risks and French Elections: Sterling Update
Here’s the latest currency news from our partner Moneycorp, to help you find out what your money is worth.help you find out what your money is worth.
Oil prices have jumped this morning following news that the US has rejected Iran’s proposals for the reopening of the Strait of Hormuz. Iran responded by indicating that it would not soften its demands.
Even so, the US President has suggested that he expects negotiations to restart this week, despite the apparent impasse between the two sides.
What is clear is that the Gulf States are suffering from the problems in the Middle East, something that looks set to continue as we head towards winter in Europe, North America and parts of Asia, which will likely drive up demand for both fuel oils and gas products.
Meanwhile, the threat of a US diesel export ban has prompted diesel prices to surge across Europe. In my view, upward pressure on energy prices is likely to persist as we approach the next round of interest rate decisions from major central banks.
A gathering storm for the UK as fuel prices jump again
The UK looks particularly exposed to higher energy prices. Limited domestic production and a lack of increased licensing agreements for North Sea developments mean the UK is unable to fully benefit from higher tax revenues generated by oil and gas extraction, nor strengthen its gas and fuel storage capacity. As a result, it retains some of the lowest storage levels in the Western world.
This is not solely a current government issue. Previous governments also focused on expanding renewable energy production while overlooking the need for significant redundancy in energy generation capacity.
The backdrop for the upcoming Budget is therefore becoming increasingly challenging. Prime Minister Andy Burnham and Chancellor John Healey would have preferred to frame the Budget around building for the future, but present‑day challenges may well overwhelm that narrative.
The risks of higher inflation, lower growth and weaker employment will continue to ratchet up pressure on the public finances, which are already overshooting. As such, the risks to GBP against other major currencies remain skewed to the downside, even as the risks to interest rates lie in further hikes from here.
French Presidential poll suggests a Mélenchon‑Le Pen run‑off, focus on provisional September CPI
According to a poll conducted for M6 and RTL, the most likely first‑round Presidential election outcome would see Marine Le Pen comfortably secure first place, ahead of Jean‑Luc Mélenchon in second place and Edouard Philippe in third. In a subsequent run‑off, Le Pen would defeat Mélenchon by 69% to 31%, while a contest against Philippe would be closer, with Le Pen leading 57% to 43%.
It is clear that the National Rally party currently has momentum. However, French voters have been here before during the 2024 parliamentary elections, when a coalition of parties sought to prevent National Rally from taking power. That outcome has nevertheless left French politics in turmoil, with several Prime Ministers resigning following the unpopularity of Budgets presented to a divided parliament.
Meanwhile, this week brings a number of provisional September national CPI releases, including figures from Spain, France and Germany, culminating in the Euro Area aggregate reading on Friday. Headline inflation is expected to record a further increase, while core CPI is expected to remain largely unchanged. This could push yields higher still and yet, in my view, should not offer the euro support against most other major currencies given that yields are rising across markets.
Canada’s secession vote a damp squib, US‑Mexico trade discussions mooted
Alberta’s proposed secession from Canada will be put to a vote in a few weeks’ time, but the latest polling suggests the exercise is unlikely to change anything. More than 70% of respondents would vote to remain part of Canada, while only 23% favour leaving. As such, this ought to put to bed future suggestions of separation while dealing a blow to any ambitions elsewhere to break away from Canada.
Monthly GDP figures from Canada are due tomorrow and may attract some attention. However, with Canadian employment data running a week out of sync with US figures, the focus for CAD may centre on preventing further losses after its three‑week losing streak against the USD pushed USDCAD to multi‑month highs.
As for Mexico, the central bank held interest rates unchanged last week and now faces the prospect of renewed pressure from the US after comments over the weekend from US Trade Representative Jamieson Greer. The US is seeking discussions aimed at reducing the “ballooning” trade deficit with Mexico. Perhaps the US should look closer to home, and to the rise in energy prices and global inflation, when considering why that deficit has widened sharply over the past four months. In my view, the MXN is likely to remain under pressure this week.
US September payrolls report likely to set the tone for future Fed decisions
The US September payrolls report is due on Friday and is likely to be the release that attracts the greatest attention from financial markets. August payrolls were significantly stronger than expected, but questions remain over why that occurred and whether such strength can be sustained, particularly given the weakness in economic activity seen in recent quarters.
Should the payrolls report show net job growth of more than 100,000, markets will quickly increase their expectations for both the number and frequency of further Fed rate hikes. However, a figure below 50,000 would undermine confidence in another hike before year‑end, in my view.
Ahead of payrolls, the US calendar includes secondary labour market releases, final Q2 GDP figures, August PCE inflation data, August trade balance figures and September ISM manufacturing data.
It could prove an interesting week in determining whether the USD cements its recent strength, gives some of it back, or builds further momentum. With US yields rising again today, the risks to the USD remain skewed to the upside, in my view.
Why Moneycorp?
With a Platinum Trusted Service Award 2020 from independent review site Feefo and 40 years of experience in the industry, FrenchEntrée has been recommending Moneycorp for more than 15 years. During this time they have helped thousands of client planning the best way to pay for their property as well as supporting them afterwards with any further payment from paying bills, mortgages to repatriating UK pension payments for those who have retired to France.
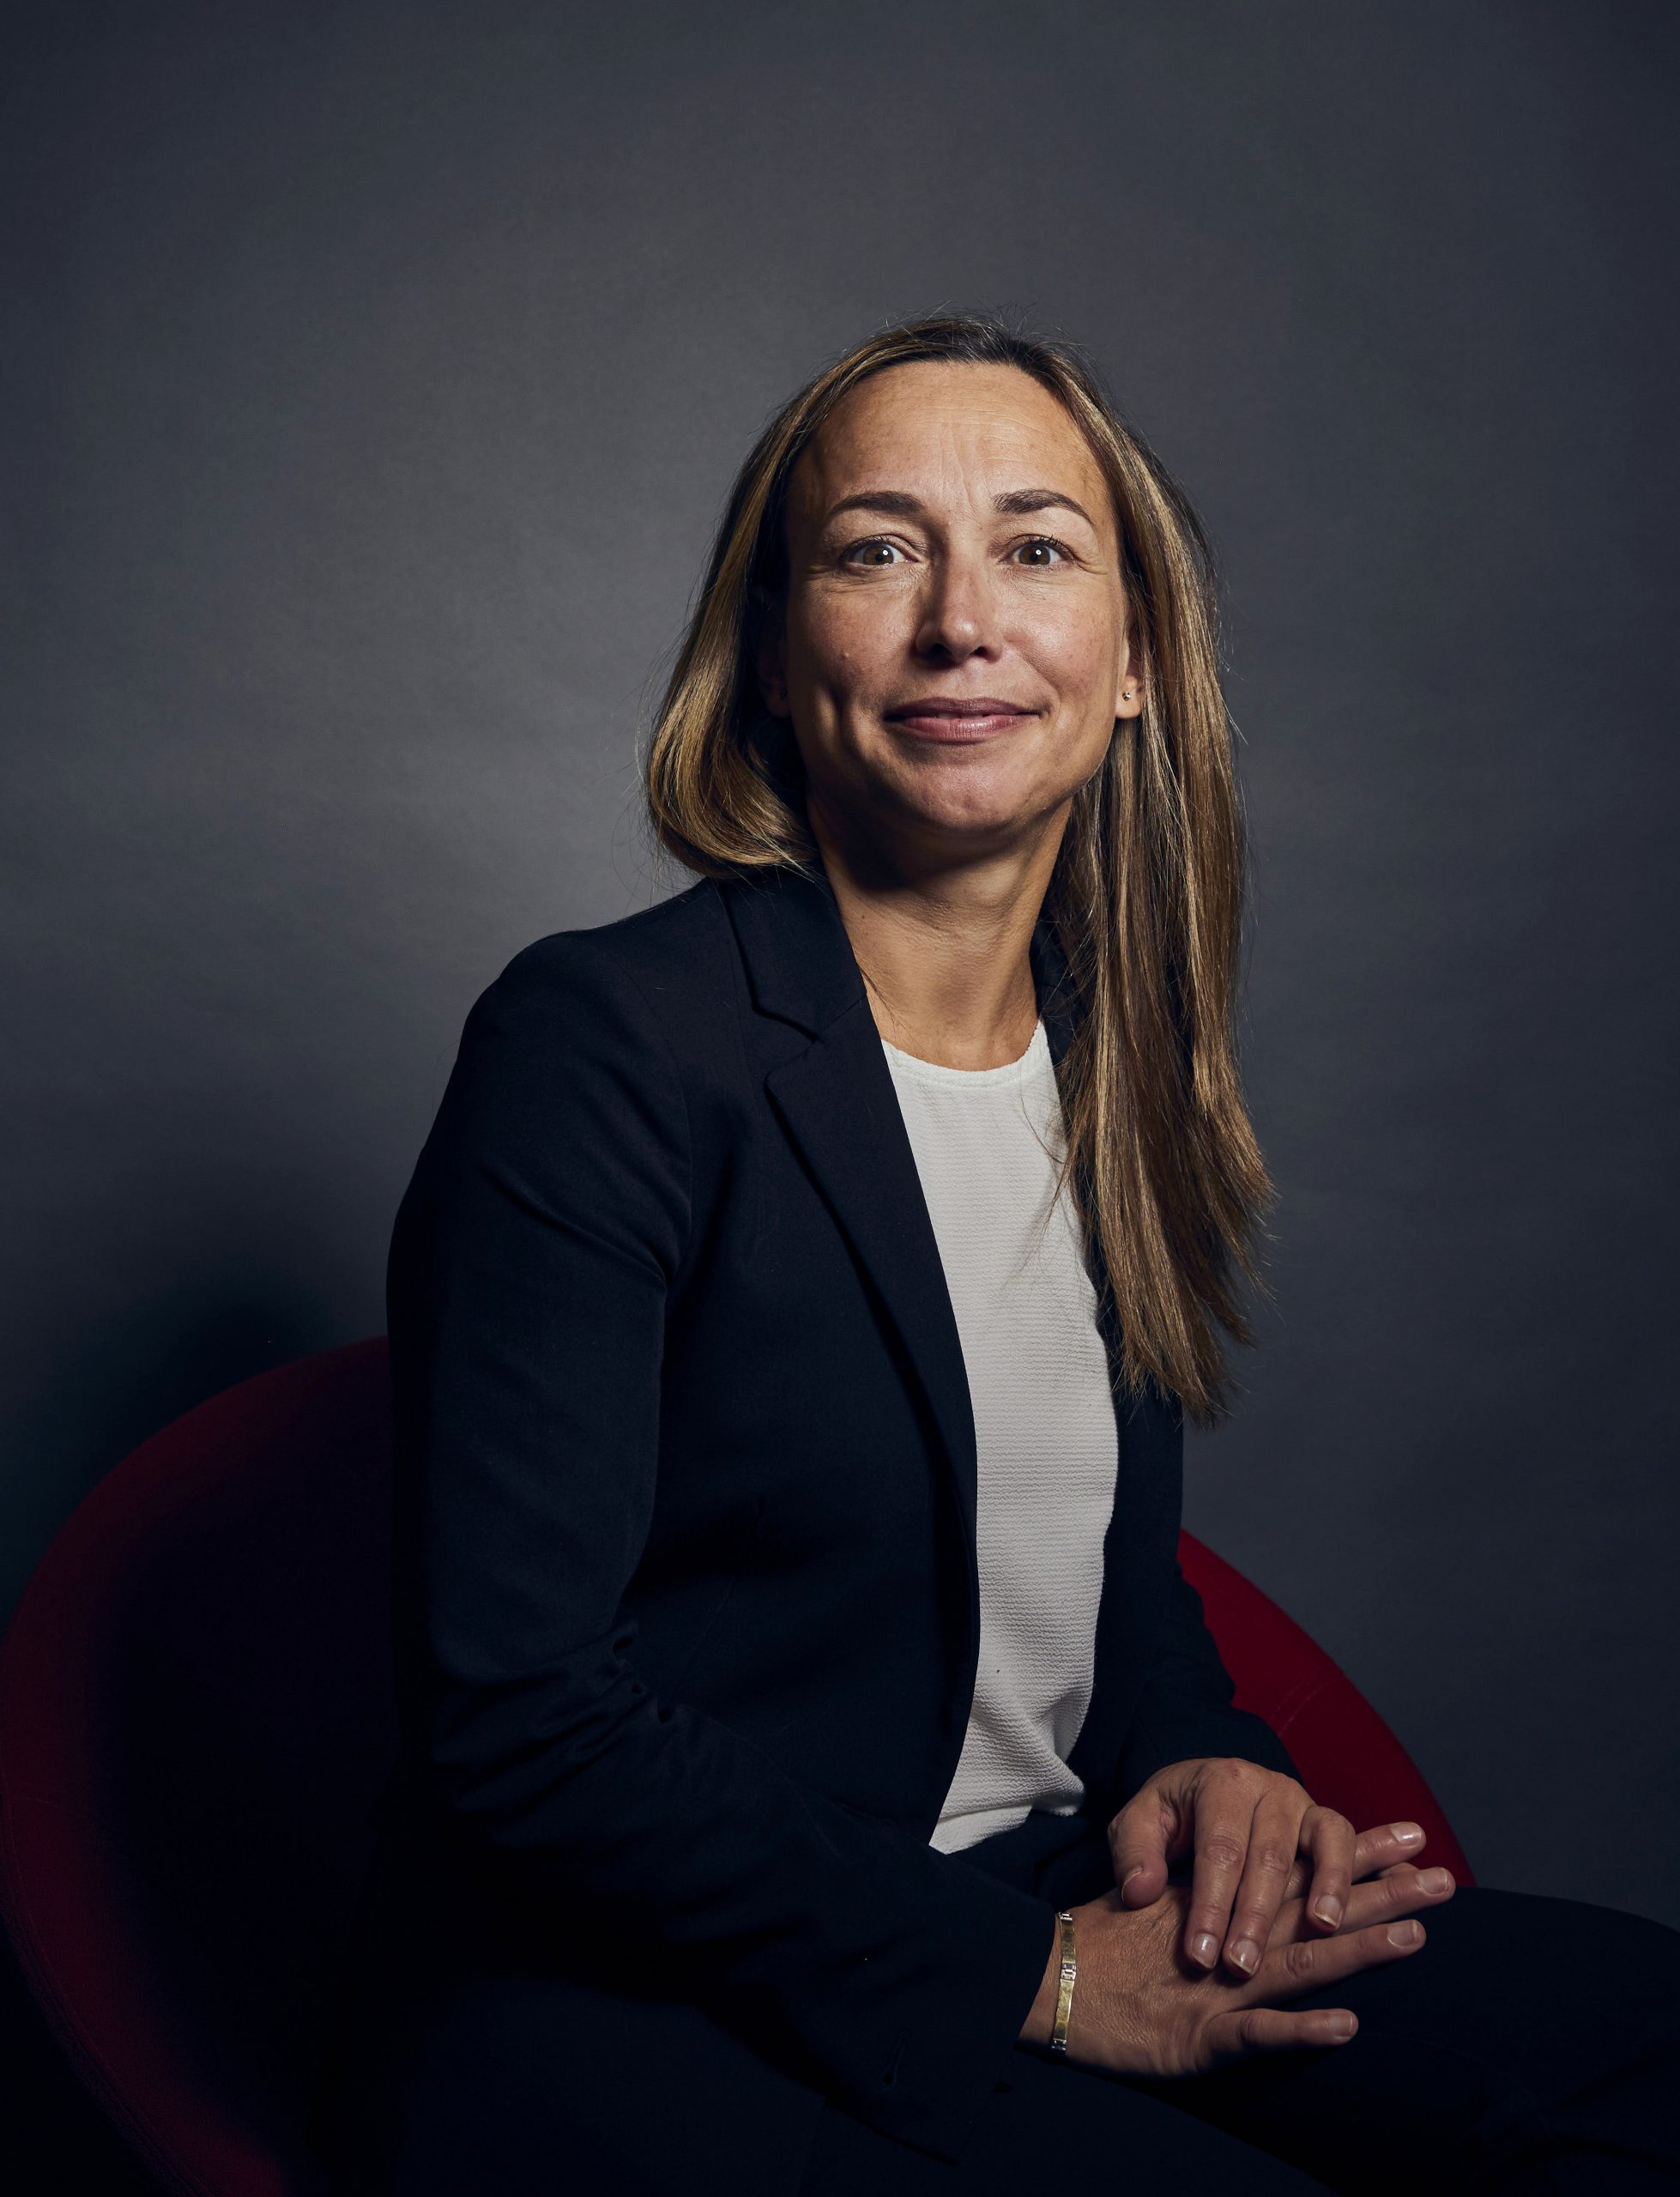
Furthermore, we have worked with the same person at Moneycorp for more than a decade! You might be familiar with her as she often writes for our French Property News magazine. She has 13 years’ experience in foreign exchange, and is a qualified European lawyer with experience in European transactions. Mar will be happy to answer any questions or enquiries to support you through these difficult times
Opening an account is really easy and free of cost. You can register online or over the phone in a couple of minutes and for FrenchEntrée readers there are no transfer fees in any payment.
Share to: Facebook Twitter LinkedIn Email
Related Articles
Leave a reply
Your email address will not be published. Required fields are marked *