UK Budget, Iran Tensions and Interest Rates: Sterling Update
Here’s the latest currency news from our partner Moneycorp, to help you find out what your money is worth.
Global economic uncertainty continues to influence currency markets, with investors weighing geopolitical developments, energy prices and the outlook for inflation. These factors remain important for sterling and the euro, as any changes in market sentiment could affect exchange rates for people transferring money to or from France.
In Europe, attention remains on France’s economic outlook and political uncertainty, with concerns over public finances and the wider economic environment potentially weighing on the euro. Sterling’s performance against the single currency will continue to depend on developments on both sides of the Channel, as investors assess the relative strength of the UK and eurozone economies.
Looking ahead, markets will be watching closely for fresh economic data and signals from central banks to gauge the likely direction of interest rates. Inflation trends, growth figures and political developments could all influence sterling’s next move against the euro. For anyone buying property in France, moving savings or managing regular payments between the UK and France, exchange rate movements remain an important consideration.
Iran warns of a response “several times greater” to any renewed US strikes
Tensions in the Middle East have risen again over the weekend. US intelligence has reportedly warned that Iran has substantially increased efforts to target American officials both in the region and abroad, prompting the State Department to update travel advisories for fourteen Middle Eastern countries. President Trump has said he is weighing a renewed military response against Iran, while an Iranian military official warned that any limited action by the US would be met with a response “several times greater”, citing the country’s current state of readiness.
Separately, President Trump accused Iran of fabricating reports of tanker attacks in the Strait of Hormuz in order to drive up oil prices ahead of the upcoming US elections, a claim Iran denies. Attacks on shipping and regional targets continued over the weekend, including intercepted missile strikes on Saudi Arabia.
On Russia and Ukraine, there was a more constructive development. The two sides agreed on Friday to a localised ceasefire in the Russian‑occupied town of Oleshky, brokered through US First Lady Melania Trump, due to take effect this week and allowing humanitarian aid deliveries and civilian evacuations. Separately, negotiators from Ukraine, Russia and the US have agreed to hold technical‑level peace talks in Abu Dhabi in the first half of November.
It’s worth treating this as an early, localised step rather than a broader breakthrough: Russia continues to demand that Ukraine cede additional territory in the Donbas region, which Kyiv has rejected, and both sides continue to exchange long‑range strikes elsewhere along the front line.
For FX, the net effect of these developments has been a modest pickup in demand for traditional safe havens, alongside continued volatility in oil prices, both relevant for GBP, EUR and commodity‑linked currencies this week.
All eyes turn to Wednesday’s UK Budget
Chancellor John Healey delivers his first UK Budget this Wednesday, 28 October, and it arrives at an unusually sensitive moment. A sustained rise in UK government borrowing costs this year has significantly narrowed Healey’s fiscal headroom, down from an estimated figure in the twenties of billions of pounds back in the spring to somewhere between roughly £11bn and £20bn today, depending on the estimate used, with the Institute for Fiscal Studies’ own figure sitting at the higher end of that range. UK government borrowing also came in close to £2bn above official forecasts in September, adding further pressure.
Expectations are for a cautious Budget focused on reassuring bond markets rather than major new spending commitments, with reports suggesting the Chancellor favours stability over the bigger fiscal ambitions floated earlier this year by Prime Minister Burnham.
The key dynamic for sterling is less about the specific policies announced and more about how credible the plan appears to bond investors. A Budget seen as fiscally disciplined could help ease the recent rise in borrowing costs and support the pound, while one seen as over‑committing on spending risks pushing yields higher for the wrong reasons, a dynamic the market has been particularly alert to since the 2022 mini‑Budget episode.
Notably, investors have so far been considerably less alarmed by the UK’s fiscal position than by France, Italy or the US, which has helped keep sterling relatively resilient near multi‑month highs against the euro heading into Wednesday.
The Federal Reserve meets Wednesday, with markets strongly favouring a hold over a third consecutive hike
The Federal Reserve’s policy meeting concludes on Wednesday, the same day as the UK Budget, with the decision and Chair Kevin Warsh’s press conference due in the evening, UK time. Having raised rates in September for the first time in around three years, the Fed is now widely expected to pause this week, with prediction markets and futures pricing putting the odds of a hold at somewhere around 90%, and a further quarter‑point hike a much less likely outcome.
A December hike remains the market’s preferred window for any further tightening this year and is seen as considerably more probable than an October move.
Warsh has continued to steer away from giving forward guidance on the pace of future moves, repeatedly declining to pre‑commit to a particular path at recent public appearances. This has kept markets leaning more heavily on incoming data than on central bank signalling.
With the Fed broadly expected to hold steady, the greater source of volatility for the dollar this week may come from Wednesday’s UK Budget and Thursday’s ECB decision landing in such close succession, rather than from the Fed announcement itself.
EUR remains broadly stable as softer eurozone business activity reinforces expectations of an ECB pause this week
The euro has traded broadly stable through the weekend, having stabilised somewhat after a period of underperformance driven by French fiscal concerns. Last week’s flash business activity survey data came in weaker than expected across the eurozone, with France’s reading pointing to continued contraction, reinforcing market expectations that the European Central Bank will hold rates steady at its own meeting on Thursday, the day after both the UK Budget and the Fed decision.
Encouragingly, peripheral eurozone bond spreads, including France’s, have narrowed somewhat as the most acute flight‑to‑quality pressure of recent weeks has eased, even as energy prices continue to push inflation expectations higher across the region.
CAD eases back as safe‑haven demand fades and oil prices retreat from recent highs
The Canadian dollar has given back some of last week’s strong gains, as a reduction in near‑term safe‑haven demand, following President Trump’s comments ruling out an immediate strike on Iran, has taken some of the edge off oil prices after their recent climb
Given how closely CAD has tracked the oil price and Middle East headlines in recent weeks, this pullback illustrates how quickly sentiment can shift in either direction. The Bank of Canada does not meet again until later this week, and markets continue to assign a meaningfully elevated probability to a rate hike at that meeting, a dynamic that remains a key underlying support for the currency even on a quieter day for oil.
MXN weakens towards a one‑year low as the US‑Mexico interest rate gap continues to narrow
The Mexican peso remains under pressure, trading close to its weakest level in around a year as the interest rate differential between the US and Mexico continues to narrow. Banxico has held its policy rate steady in recent months, and markets are placing a high probability on it remaining unchanged again at its upcoming November meeting, while the Federal Reserve’s September hike and the prospect of further tightening into year‑end continue to erode the peso’s traditional carry‑trade appeal relative to US assets.
Broader Middle East‑driven risk aversion has added to the pressure in recent sessions, though some of that effect eased over the weekend as acute escalation fears cooled slightly. With a relatively light Mexican data calendar this week, the currency is likely to remain primarily driven by US dollar sentiment around Wednesday’s Fed decision and the broader geopolitical backdrop.
Why Moneycorp?
With a Platinum Trusted Service Award 2020 from independent review site Feefo and 40 years of experience in the industry, FrenchEntrée has been recommending Moneycorp for more than 15 years. During this time they have helped thousands of client planning the best way to pay for their property as well as supporting them afterwards with any further payment from paying bills, mortgages to repatriating UK pension payments for those who have retired to France.
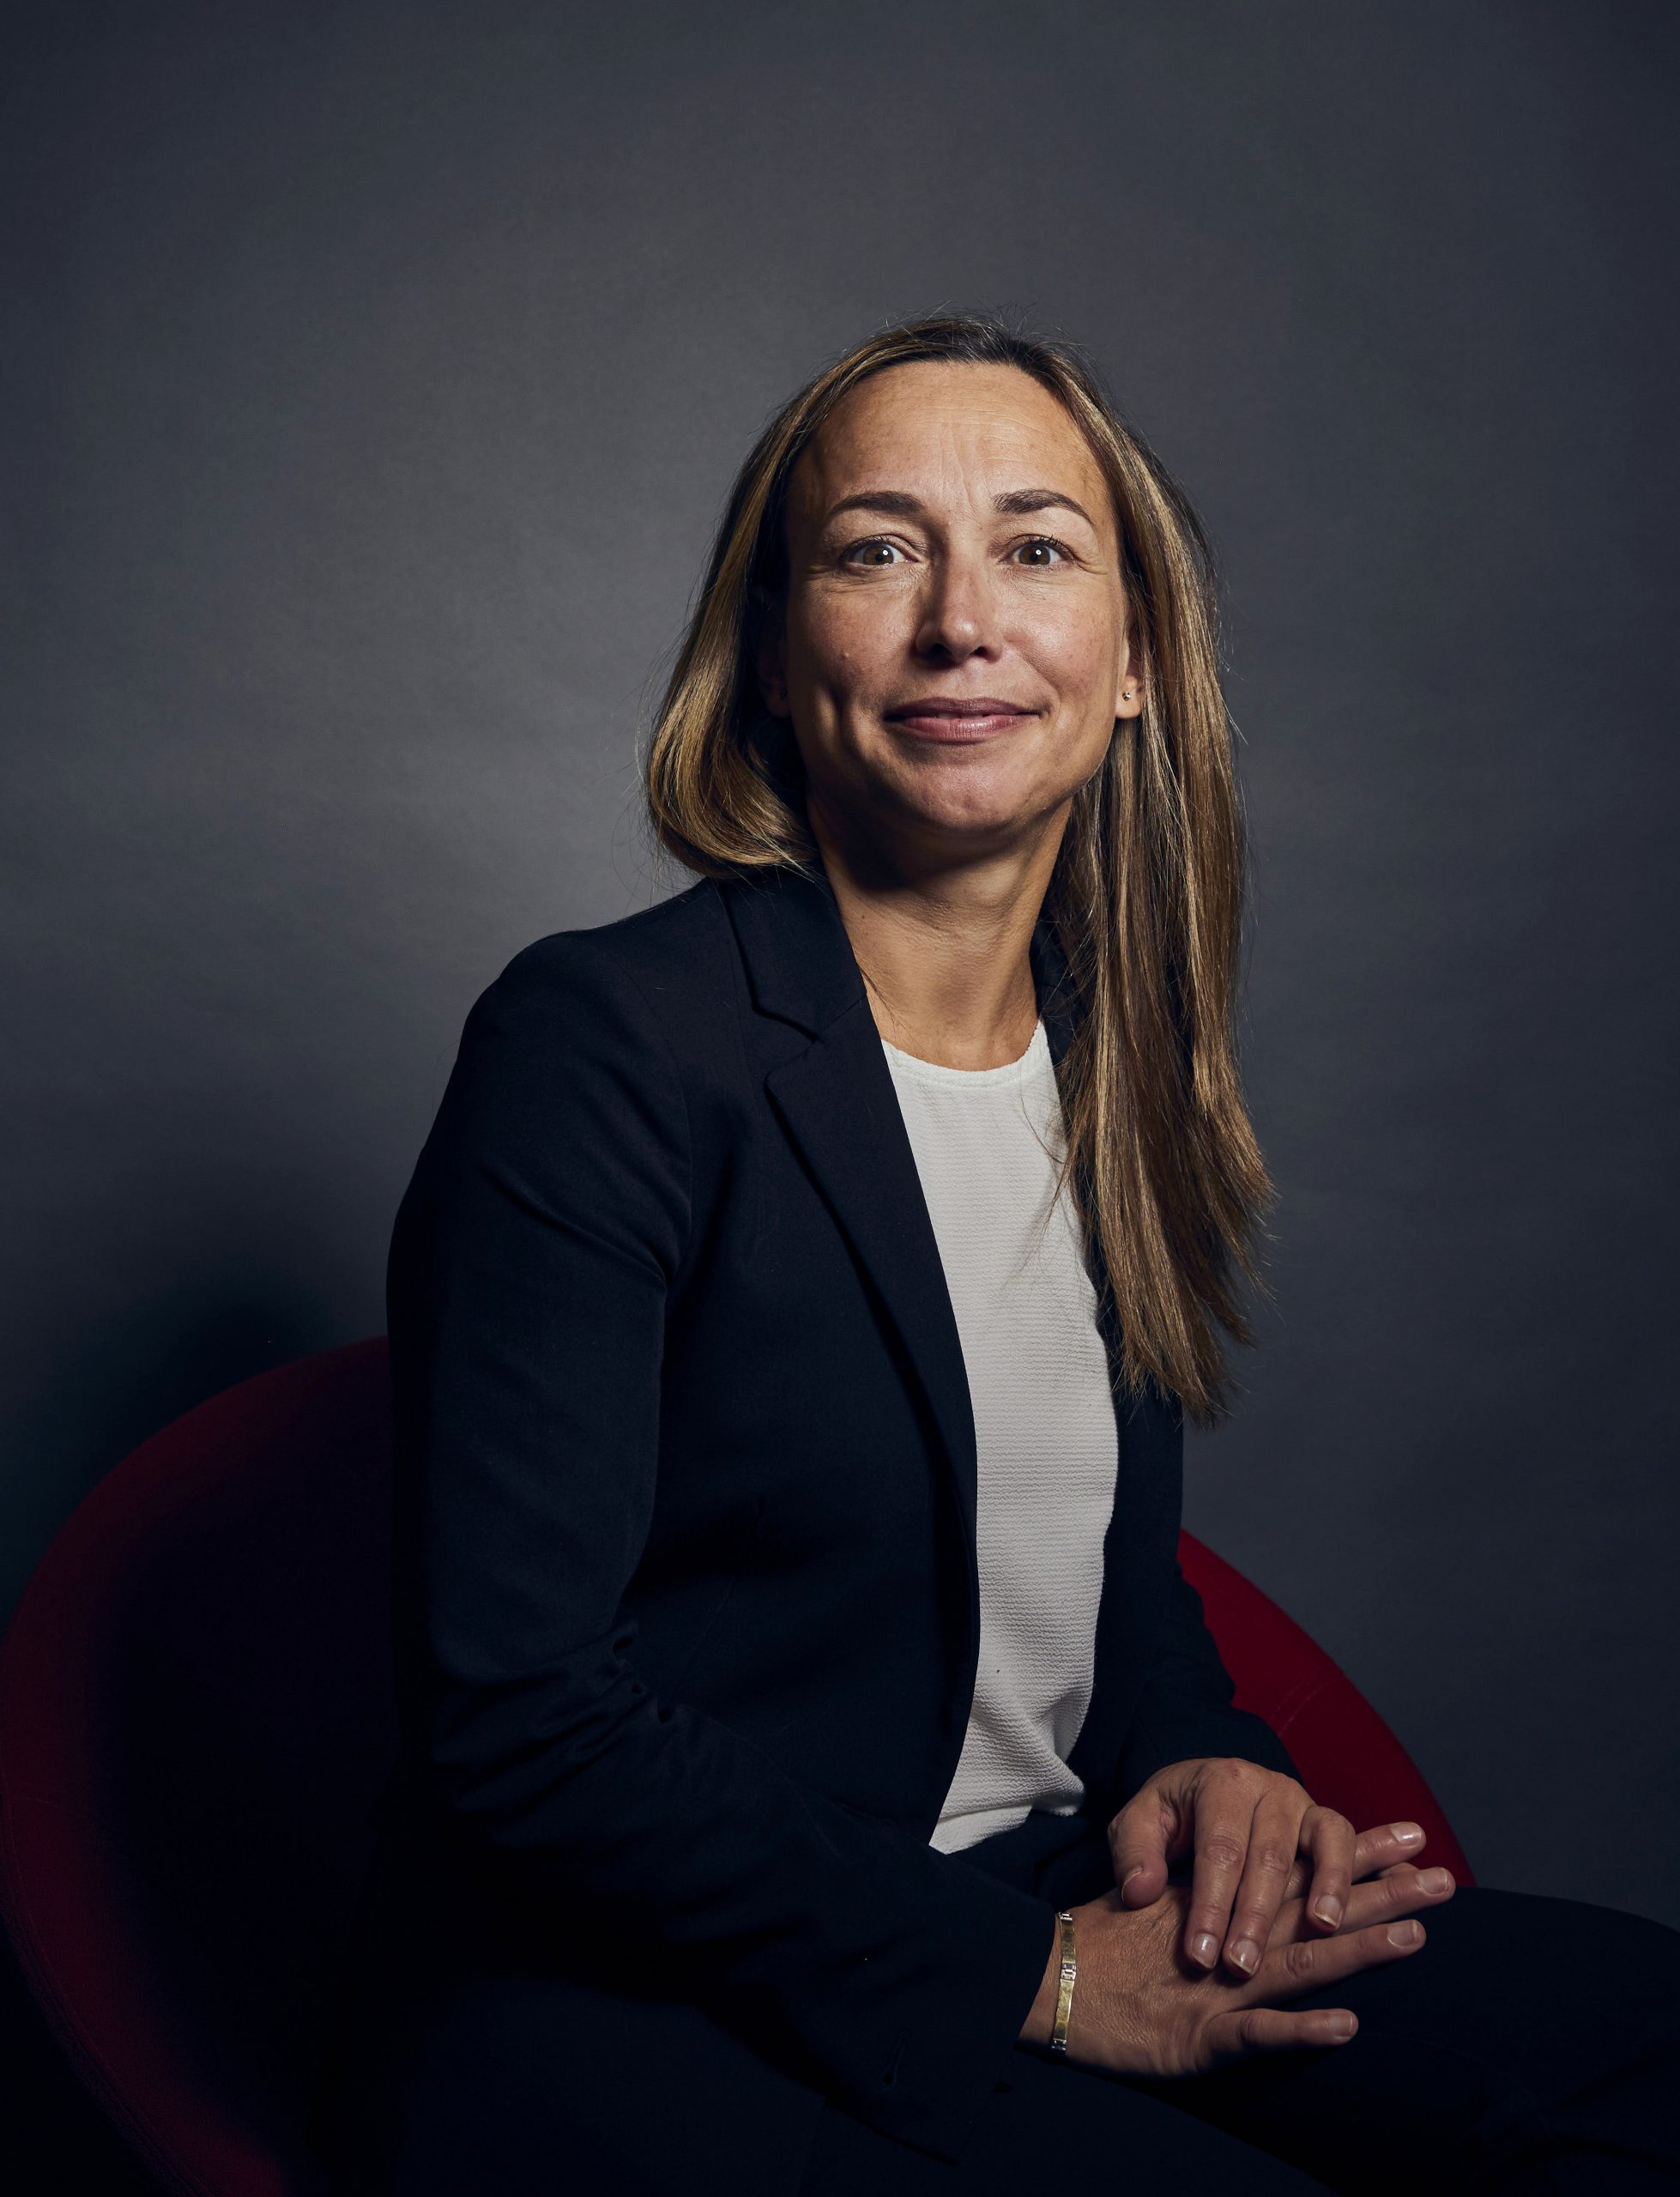
Furthermore, we have worked with the same person at Moneycorp for more than a decade! You might be familiar with her as she often writes for our French Property News magazine. She has 13 years’ experience in foreign exchange, and is a qualified European lawyer with experience in European transactions. Mar will be happy to answer any questions or enquiries to support you through these difficult times
Opening an account is really easy and free of cost. You can register online or over the phone in a couple of minutes and for FrenchEntrée readers there are no transfer fees in any payment.