Sterling Eyes Central Bank Week as Fed and BOE Face Tough Calls: Sterling Update
Here’s the latest currency news from our partner Moneycorp, to help you find out what your money is worth.
This week’s Fed meeting, due to announce its interest rate decision at 7pm BST on Wednesday, has been preceded by a significant amount of conflicting data. That culminated on Friday with August CPI figures, which continued to report subdued core inflation. The challenge for the Fed is that the data are pointing in different directions, providing no clear picture of the current state of the US economy, labour market, or inflation pressures.
Also released on Friday was the preliminary September University of Michigan consumer sentiment figure, which recorded another sharp decline in sentiment after recently recovering from the lows reached in May. Will that translate into weaker retail sales figures for the remainder of Q3, with August figures due just ahead of the Fed decision?
The risks to US economic growth, the negative effects of high necessity goods prices on discretionary spending, and signs of ongoing sluggish labour demand would all argue against a Fed hike. However, inflation risks offer a significant counterargument. Market forecasters think the Fed will stand pat, but Bloomberg interest rate probabilities assign an almost 90% chance of a hike.
As for the USD, I think it may struggle for headway this week, despite the improvement seen late last week against most major currencies, especially if the Fed defies market pricing and leaves rates on hold.
What will this week’s data deluge and BOE tell us after last week’s stronger activity figures for July?
Last week concluded with a strong July UK activity outturn, driven by strength in services, which may have tested the BOE’s patience regarding its policy hold strategy. The BOE meeting concludes on Thursday at midday. Market forecasters are unanimous that there will be no change, while Bloomberg interest rate probabilities estimate roughly a one‑in‑five chance of a hike.
Ahead of the BOE decision, the UK releases labour market data for July and August, along with August CPI figures, both of which could prompt a shift in rate hike probabilities. There have been some signs that the UK labour market may be set to improve, which would represent a welcome shift from the deterioration seen over the past two‑plus years.
However, aside from the employment and unemployment figures, weakness in average earnings will again be a focus. If these continue to show a further slowdown in growth compared with previous months, that could continue to squeeze disposable incomes. As for CPI, headline inflation is forecast to rise back above 3%, while core inflation is expected to remain steady at 2.6% y/y.
Following the BOE decision, GfK consumer confidence, retail sales, and public finances data are released. None of these are likely to offer support to GBP, but developments elsewhere may still leave sterling stronger against the USD and potentially other major currencies as well.
ECB’s hike in the face of headline inflation pressures could backfire, if followed up with more
The ECB raised official rates last week in a move that surprised nobody. The subsequent press conference contained numerous contradictions, but it did appear to hint at further hikes, despite weakness in the Euro Area economy and ongoing headwinds facing key sectors such as autos and engineering, given the renewed tariff regime from the US and other countries.
Growth is set to remain weak, despite ECB officials putting a brave face on developments, particularly with public sector expansion set to crowd out the private sector through higher debt financing costs and the prospect of higher taxation.
There are no particularly significant releases due this week, with September German ZEW figures unlikely to materially alter the outlook for the Euro Area economy or sentiment towards the euro. Consequently, the focus is likely to remain on developments elsewhere and the stream of comments from ECB officials due between now and the end of the week.
Canada PM pushes for closer EU ties after US trade talks collapse
According to a Wall Street Journal article, Canadian Prime Minister Mark Carney has sought to foster deeper ties with Europe as relations with the US continue to deteriorate.
The same article highlighted potential cooperation in energy, AI, and defence, including the joint construction of AI data centres, cloud storage infrastructure, and new satellite networks.
The deterioration in trade relations between Canada and the US is, in my view, an own goal for both sides. The US could potentially cause lasting damage to trade relationships covering energy, car parts, travel, and construction imports from Canada. At the same time, Canada could face higher costs for some agricultural goods, electronics and consumer products, vehicles and machinery, and defence equipment.
Today at 13:30 BST, Canada releases August CPI figures. Could these force the hand of the Bank of Canada on interest rate hikes? I do not think so, as Canada has experienced some of the smallest increases in CPI inflation since the conflict in the Middle East began.
Chances of US‑Iran peace deal remain remote as Hormuz talks between Iran and Gulf States delayed
A meeting planned for today between Gulf nations and Iran, aimed at establishing a temporary shipping lane through the Strait of Hormuz, has been postponed, according to Oman’s Foreign Minister.
Reports suggest that disagreement over details, including fees that Iran planned to introduce, prevented an agreement from being reached, despite a flurry of diplomatic activity that included a rare meeting between officials from Tehran and Abu Dhabi.
Meanwhile, the US and Iran appear unwilling to engage even through proxies on the possibility of a ceasefire, although there was no escalation in strikes between the two sides over the weekend.
Oil prices continue to rise, which is likely to prove harmful to the President and Republican Party ahead of the US mid‑term elections. Consequently, the possibility remains that negotiations could restart before the elections, if only to reduce pressure on energy prices, in my view.
Why Moneycorp?
With a Platinum Trusted Service Award 2020 from independent review site Feefo and 40 years of experience in the industry, FrenchEntrée has been recommending Moneycorp for more than 15 years. During this time they have helped thousands of client planning the best way to pay for their property as well as supporting them afterwards with any further payment from paying bills, mortgages to repatriating UK pension payments for those who have retired to France.
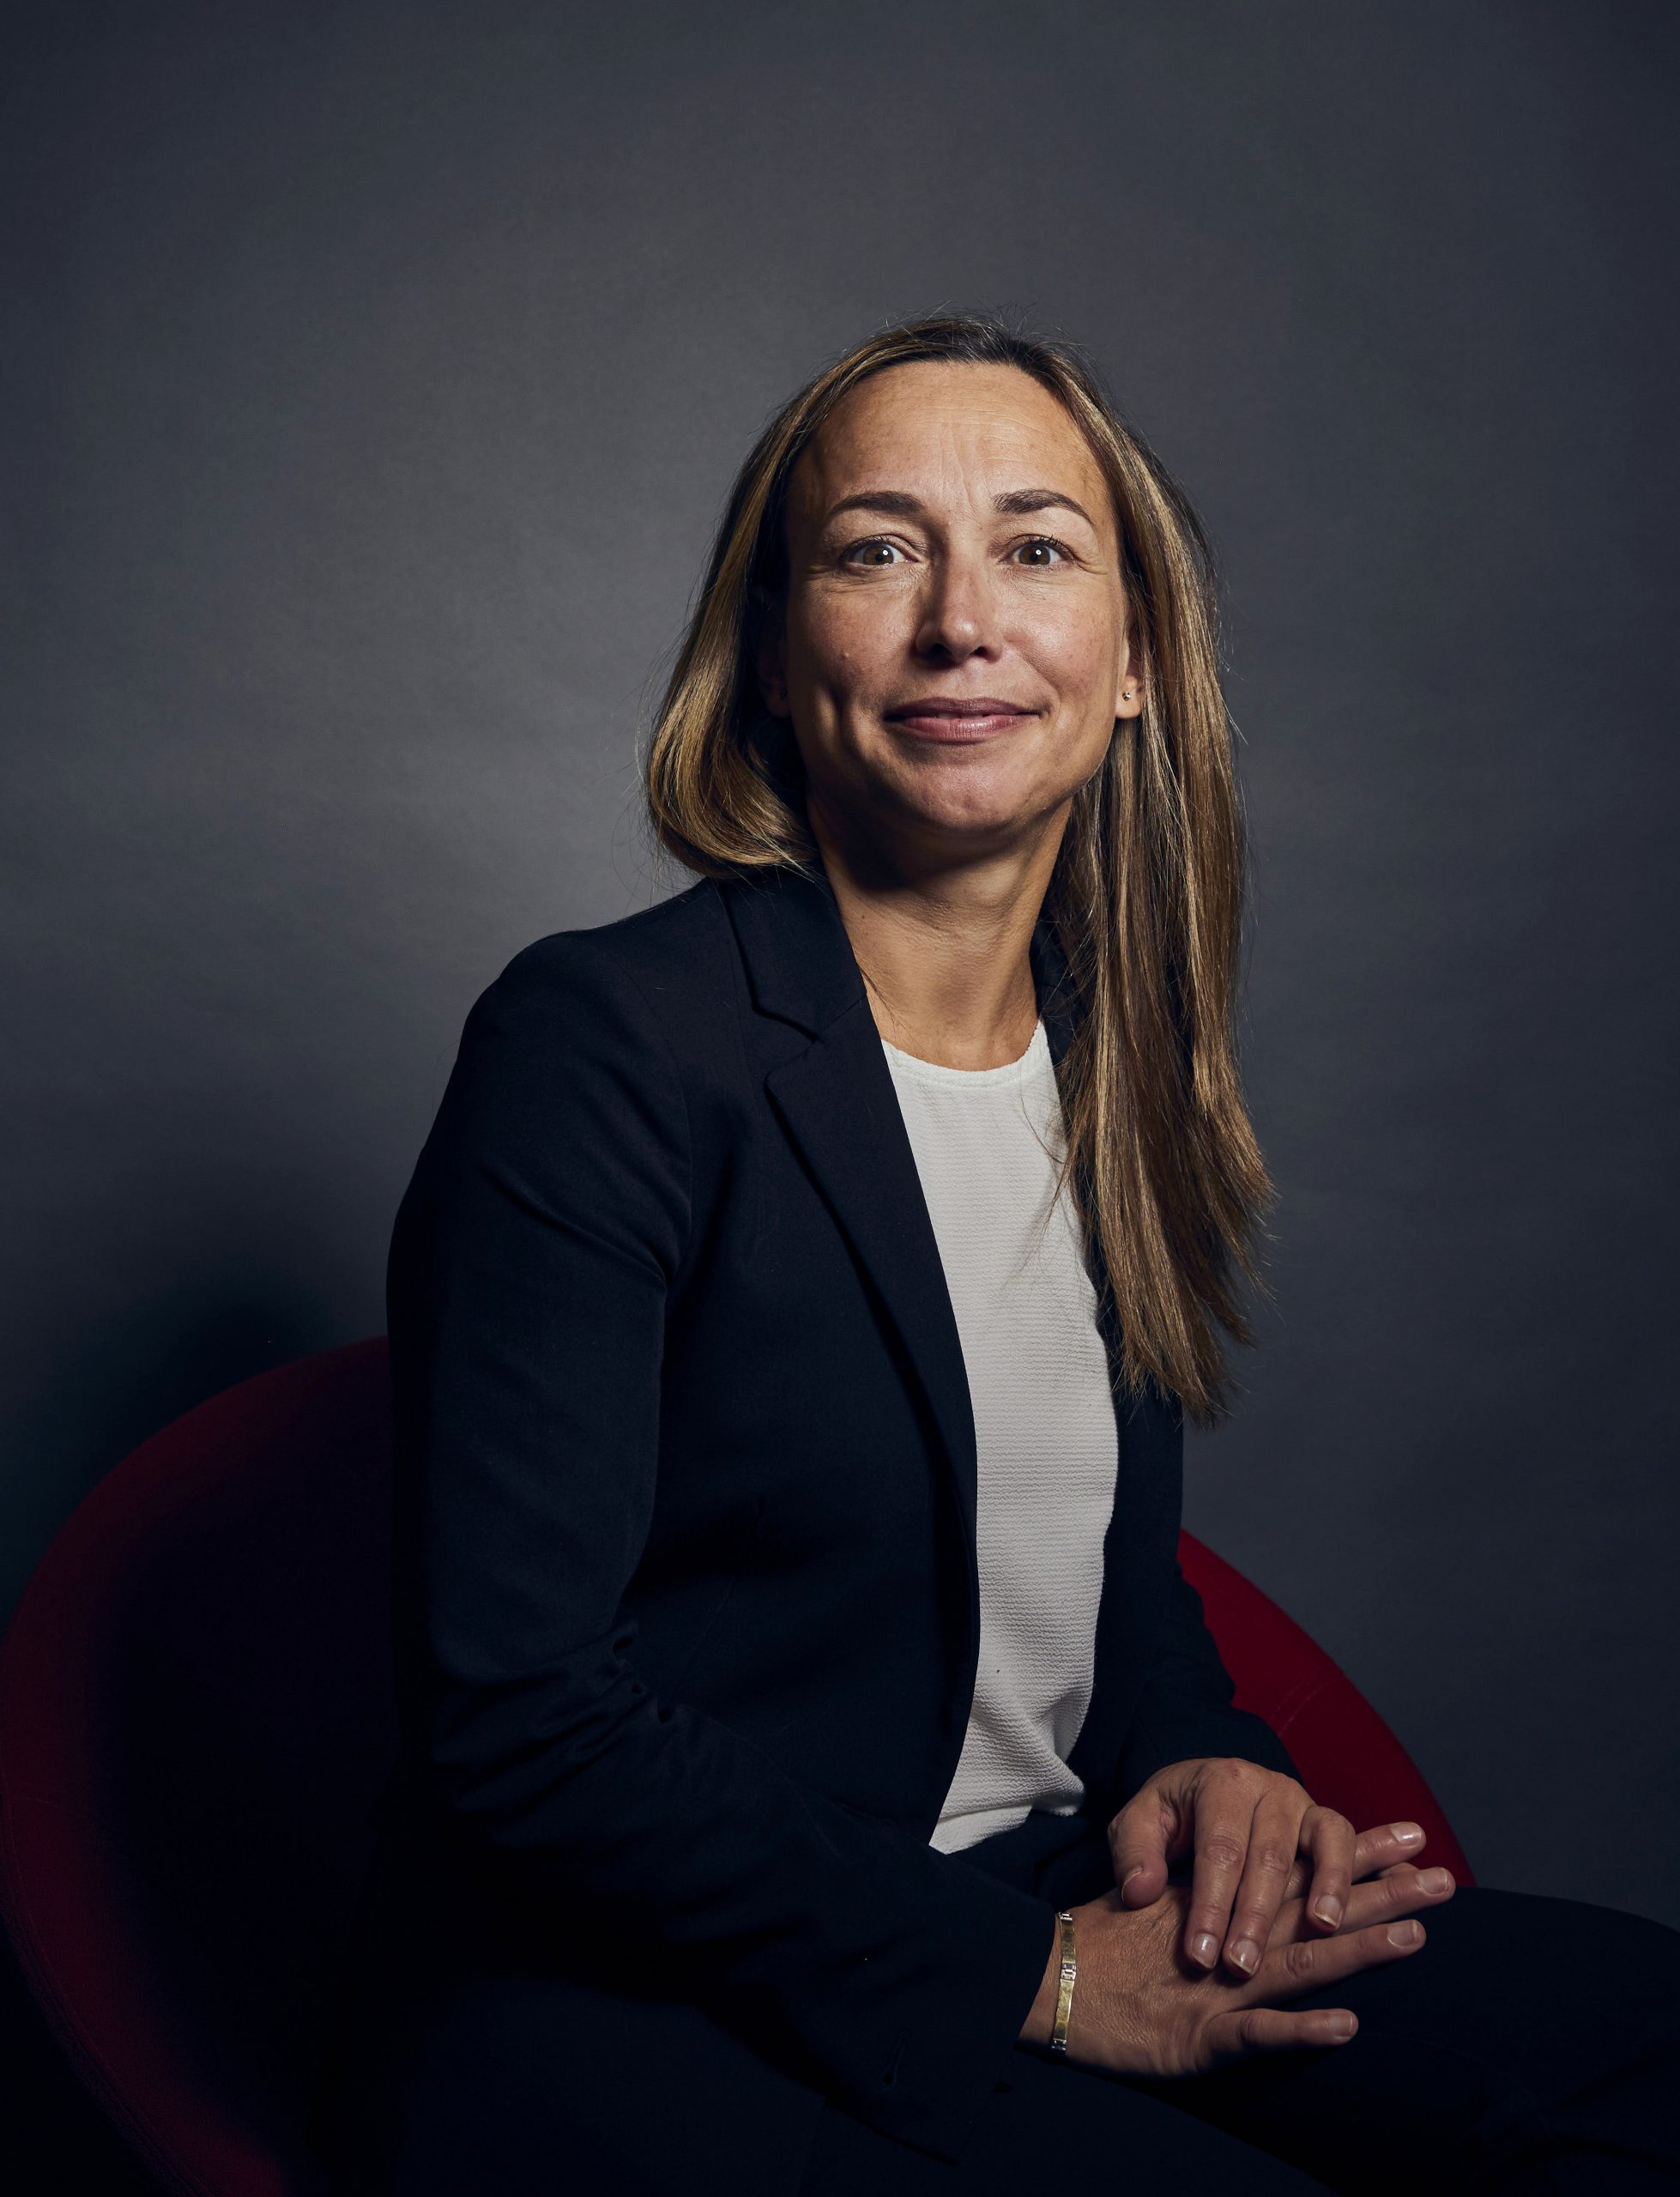
Furthermore, we have worked with the same person at Moneycorp for more than a decade! You might be familiar with her as she often writes for our French Property News magazine. She has 13 years’ experience in foreign exchange, and is a qualified European lawyer with experience in European transactions. Mar will be happy to answer any questions or enquiries to support you through these difficult times
Opening an account is really easy and free of cost. You can register online or over the phone in a couple of minutes and for FrenchEntrée readers there are no transfer fees in any payment.
Lead photo credit : Shutterstock
Share to: Facebook Twitter LinkedIn Email
More in currency, sterling, Sterling update
Related Articles
Leave a reply
Your email address will not be published. Required fields are marked *