Avoid these 6 mistakes when insuring your French second home
Buying a property in France is an exciting milestone for many UK buyers, offering a wonderful lifestyle change. Whether you are settling down permanently in a rustic Dordogne farmhouse, renovating a sunny village house in Provence, or keeping a charming coastal retreat for the holidays, setting up your overseas haven takes careful planning.
However, many British buyers run into trouble when arranging cover, assuming that property insurance in France works just like it does back in the UK. Because the French system has unique legal requirements and operational quirks, misunderstanding the finer points can leave you unexpectedly exposed.
Avoid these common pitfalls to ensure your French investment stays fully protected.
1. Assuming Insurance is Always Optional
In the UK, buildings insurance is typically a choice unless stipulated by a mortgage lender. In France, the rules are much stricter: insurance is legally mandatory for tenants, as well as for owners of apartments in a co-owned building (copropriété). While standalone house owners are technically not required by law to have cover, it is strongly recommended to protect against third-party liabilities, and virtually all mortgage lenders will make it a strict condition of your loan.
2. Overlooking the “Vacancy Clause”
This is one of the most frequent traps for holiday home owners. Because second homes can sit empty for weeks or months at a time, insurers apply strict rules regarding extended periods of unoccupation.
- Many standard policies suspend certain theft and vandalism cover if the property is left unoccupied for more than a specified number of days without specific notification or enhanced security measures.
- Winter rules may require you to turn off the water mains or drain your pipes to prevent freezing damage. Always check the fine print regarding how long your property can sit vacant.
3. Forgetting to Declare Holiday Lets
If you plan to offset your maintenance costs by renting out your French property on platforms like Airbnb, you must explicitly declare this to your insurer. Failing to mention commercial or short-term guest use can be treated as misrepresentation, potentially invalidating your entire policy if a guest causes damage or triggers an incident. A small adjustment to your premium ensures you have the correct legal and third-party protections in place.
4. Underestimating the Rebuild Cost (Valeur de Reconstruction)
In the UK, insurers often help calculate your building values automatically. In France, you are generally expected to provide an accurate estimate of what it would cost to completely rebuild the property from the ground up at current local material and labour prices. Underestimating this figure can lead to a proportional reduction in payouts if you make a claim. If you have a mortgage, check your loan documents for valuation figures, or consult a local builder or surveyor.
5. Overlooking Outbuildings, Pools, and Gardens
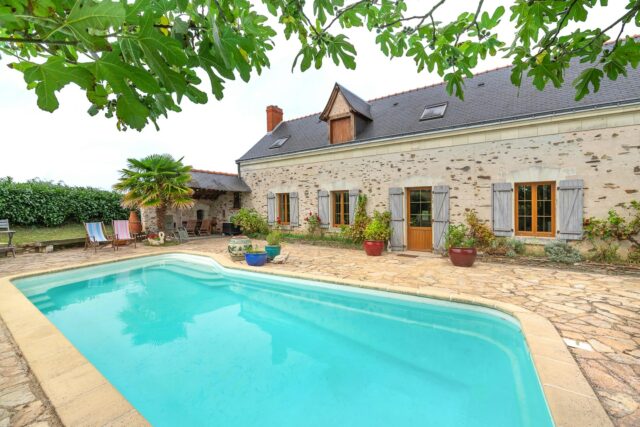
If your French property includes a detached barn, a swimming pool, a summer kitchen, or extensive boundary walls, do not assume they are automatically covered by a basic policy. Outbuildings and high-risk features like swimming pools often need to be explicitly declared and added to your policy schedule to ensure both property damage and liability are valid.
6. Missing Out on Tailored Options
Many buyers simply accept the first basic policy offered by their bank when opening a French account. However, bank-tied policies can lack flexibility for non-residents.
To find a policy that accommodates extended absences, specific security requirements, and your exact usage pattern, exploring a specialized holiday home insurance comparison platform can make all the difference. Comparing dedicated French property policies side-by-side lets you spot crucial nuances—such as English-speaking claims assistance and natural disaster extensions (catastrophes naturelles)—ensuring your overseas home is protected without paying for features you do not need.
At MyInsurance we allow you to compare holiday/second home insurance products and premiums from leading UK insurers that can provide comprehensive and specialist cover for your overseas home, including properties that are let out to third parties.
All policy wordings are in plain English and claims are dealt with by English speaking staff.
Follow this link to compare prices and save time, money and effort.