Energy tensions rise as Europe and the UK face renewed pressure: Sterling Update
Here’s the latest currency news from our partner Moneycorp, to help you find out what your money is worth.
Rising energy prices and renewed tensions in the Middle East are keeping markets on edge, with incidents in the Strait of Hormuz and further attacks in Yemen raising concerns over the outlook for energy supplies. With little sign of tensions easing, the prospect of sustained price pressures remains a concern for the global economy.
In Europe, escalating protests in France are adding to uncertainty surrounding the euro, as concerns over the country’s economic performance, Budget and forthcoming credit rating review weigh on sentiment. Sterling has reached fresh highs against the euro, while political uncertainty on both sides of the Channel could continue to influence the outlook for the single currency.
Attention now turns to a busy week for the UK economy, with inflation and labour market figures due ahead of the Budget on 28 October. The data could prove crucial in shaping expectations for the Bank of England’s next interest rate decision, with a potential rate hike in November still on the table. After recent gains against both the euro and US dollar, sterling faces an important test as markets weigh the latest economic figures against a backdrop of continued global uncertainty.
Energy prices continue to surge following incidents in the Strait of Hormuz and attacks in Yemen
Several developments over the weekend attracted market attention. In the Strait of Hormuz, reports indicated that two tankers were damaged after striking mines, prompting an immediate rise in energy prices. In Yemen, meanwhile, Iranian‑backed Houthi forces launched missiles and drones at Aden Airport, striking the site just as a passenger aircraft was preparing for departure. Separately, reports stated that the Houthis fired a ballistic missile at a major Saudi Arabian oil hub, although this was intercepted.
In a potential escalation, the UAE agreed with Saudi Arabia to re‑enter the conflict in Yemen, while Egypt announced its readiness to provide Saudi Arabia with full military support. Taken together, these developments do not suggest that tensions in the Middle East are set to ease. As a result, energy prices are likely to remain elevated in the coming weeks, despite the US President’s efforts to bring them lower.
Escalating protests in France continue to undermine the euro
Protests may be a familiar feature of French political life, but the recent demonstrations surrounding education policy and potential Budget cuts appear different and have generated greater market concern than would typically be expected. That may reflect the forthcoming Moody’s review of France’s sovereign credit rating, or the approach of the April 2027 Presidential election, where Marine Le Pen continues to lead polling for National Rally.
The protests have become increasingly violent, and French authorities have so far struggled to contain them. As a result, businesses and everyday economic activity are experiencing disruption. The French government is now considering stricter measures on demonstrations and additional powers for authorities to restore order.
Pressure on the euro remains present. The risk of these protests spreading to other countries, or materially affecting wider Euro Area economic performance, still appears limited. However, the economy’s near‑constant underperformance relative to other major developed economies remains a concern. GBPEUR has once again reached fresh highs for the year. Without progress on the situation in France, continued uncertainty surrounding the French Budget, and with a Spanish election looming in six weeks’ time, the euro could face a further challenging period against other major currencies, in my view.
The UK faces a significant week of data ahead of next week’s Budget
This week brings the release of UK labour market data (August/September), CPI figures (September), public finances data (September) and retail sales figures (September). Collectively, these releases could help shape the Bank of England’s decision on whether to deliver its first interest rate hike of the cycle.
The two key releases are likely to be CPI and labour market data, although not necessarily in that order. CPI is clearly the primary focus for the Bank of England. Markets will look not only at whether headline inflation increases again, but also whether core and services inflation follow suit. If all three measures rise, then regardless of what the other releases indicate, I think the Bank of England will opt for a rate hike in November.
If, however, the inflation picture remains more uncertain, attention is likely to return towards the outturn of the earlier released labour market data. Risks around slower average earnings growth, alongside weaker vacancies and employment figures, could keep the Bank on hold until December. That said, the November decision coincides with the next set of economic forecasts, which would provide further justification for a rate increase should policymakers decide one is warranted.
These figures arrive ahead of the UK Budget on 28 October. The public finances data could prove weak, adding to the challenges facing the Chancellor, who is seeking to direct additional spending towards priority areas without currently having the available funds to do so.
Sterling has performed well against both the US dollar and the euro in recent weeks, but could this week’s data alter that trend?
Political opposition to the temporary easing of Russia sanctions continues to build in the US
US President Donald Trump announced a temporary easing of some sanctions on Russia late last week, and opposition to that decision has emerged from both sides of the political spectrum. Congress is already seeking to overturn the President’s decision relating to Russian diesel imports and will likely add this latest announcement to the broader list of measures under review.
Despite these efforts, the latest polling data continues to paint a difficult picture for Republicans ahead of the midterm elections, with Democrats polling by as much as eight percentage points ahead nationally. The President’s own polling profile has also weakened, with disapproval ratings rising in recent months.
The Federal Reserve has now entered its blackout period ahead of the 28 October FOMC decision, while the economic calendar is relatively light beyond secondary housing market data for September and preliminary October PMI releases. None of these events is likely to generate significant market activity. However, the recent US dollar sell‑off, driven by lower Treasury yields, may prove vulnerable to interruption if inflation pressures re‑intensify, in my view.
Military base accident occurs ahead of Alberta referendum, although polling suggests the result is unlikely to be close
An accident that caused a fire at a Canadian military base in Alberta has resulted in the deaths of seven service personnel and left dozens more injured. The incident comes shortly before a referendum in the province on whether Alberta should remain part of Canada or pursue secession.
Polling suggests the result is unlikely to be close, with fewer than three in ten respondents supporting secession. Nevertheless, an incident of this nature may contribute to heightened concern within the province ahead of the vote.
The Canadian dollar ended last week on a stronger footing, supported in part by broad US dollar weakness. Support may also have come from comments by Bank of Canada Governor Macklem, who argued that higher energy prices could boost both inflation and economic growth. As Canada enters a period of heavier energy consumption, stronger earnings for some businesses appear likely. However, the negative impact of higher energy prices on household spending means the argument for stronger growth remains open to question, in my view.
Why Moneycorp?
With a Platinum Trusted Service Award 2020 from independent review site Feefo and 40 years of experience in the industry, FrenchEntrée has been recommending Moneycorp for more than 15 years. During this time they have helped thousands of client planning the best way to pay for their property as well as supporting them afterwards with any further payment from paying bills, mortgages to repatriating UK pension payments for those who have retired to France.
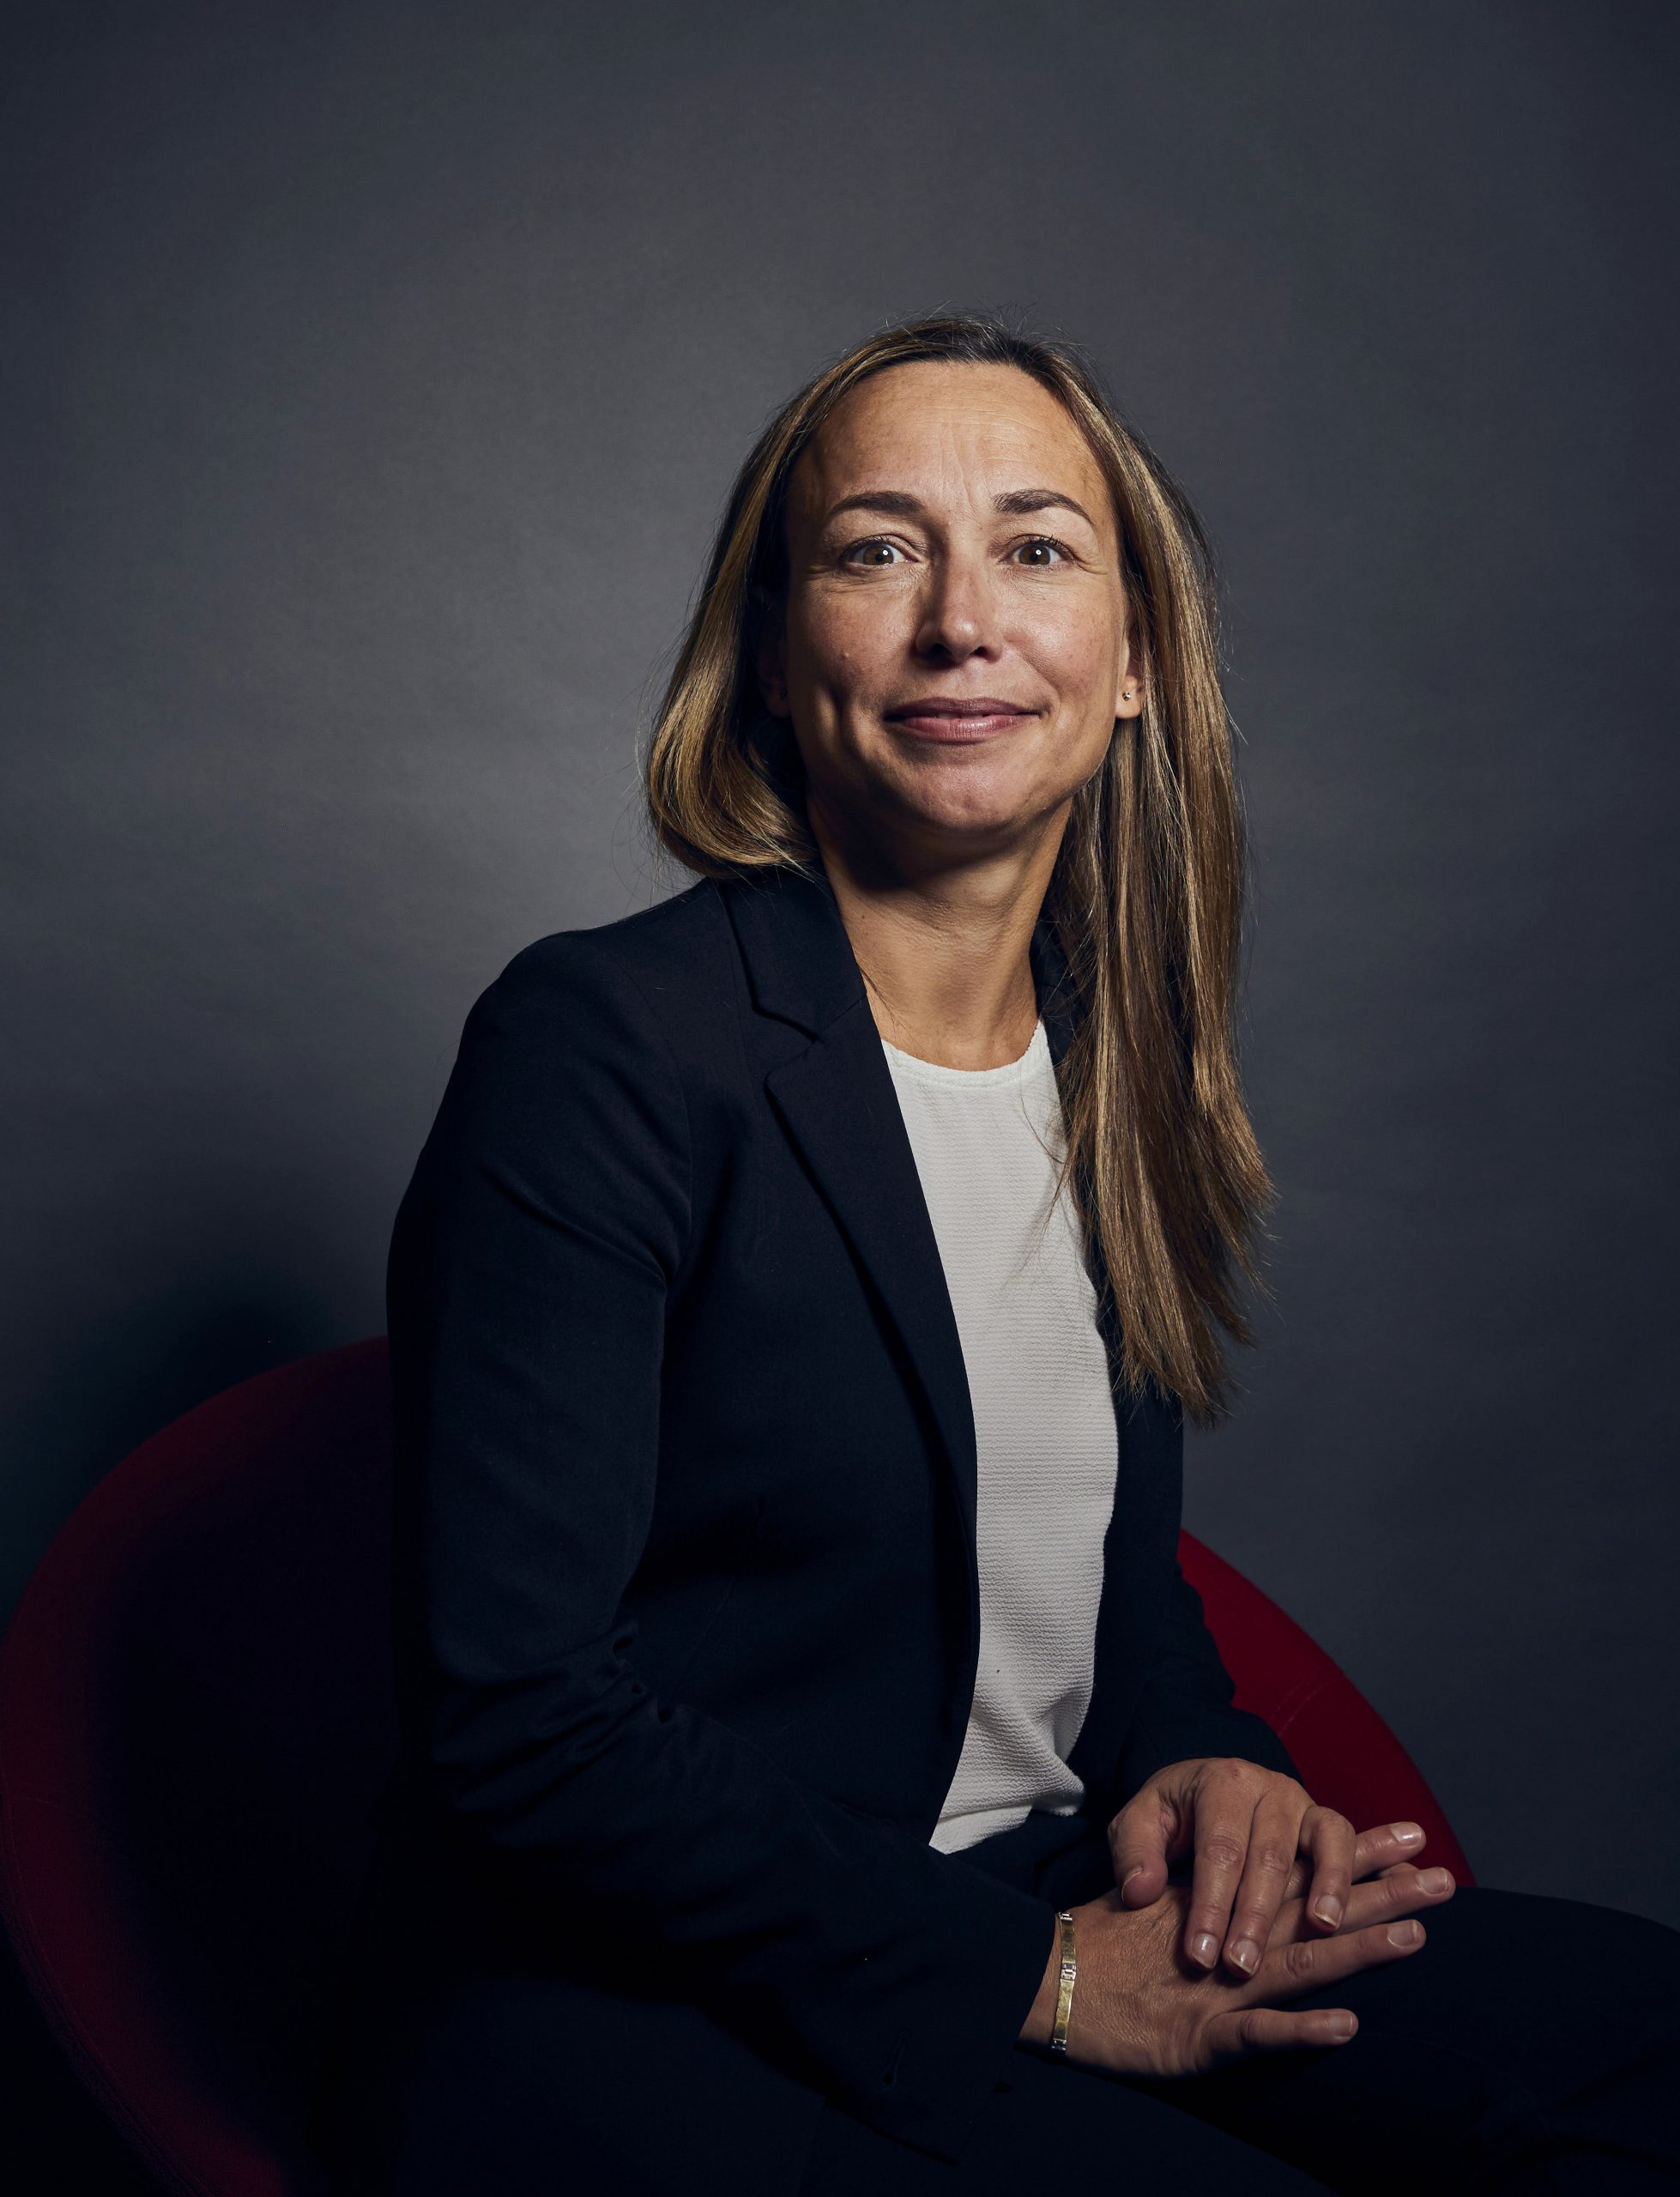
Furthermore, we have worked with the same person at Moneycorp for more than a decade! You might be familiar with her as she often writes for our French Property News magazine. She has 13 years’ experience in foreign exchange, and is a qualified European lawyer with experience in European transactions. Mar will be happy to answer any questions or enquiries to support you through these difficult times
Opening an account is really easy and free of cost. You can register online or over the phone in a couple of minutes and for FrenchEntrée readers there are no transfer fees in any payment.